Researchers
Ben Cowdock, Harry Baines Date of publication
19 October 2026
Download
Document
Concerning Developments
(1.36 MB)
Introduction
The UK property market serves as a safety deposit box for those seeking to hide illicit wealth. Real estate here retains value, can still be bought and owned anonymously using opaque trust structures, and generates substantial income through rent and sales. The rule of law and strong property rights also mean that assets are hard to confiscate, even when there is strong evidence to suspect they were bought with ill-gotten gains.
Although the precise scale of this problem remains unknown, the National Crime Agency (NCA) estimates £10 billion could be laundered through the UK property market annually.
When we started collecting these records a decade ago, we identified money laundering risks presented by off-plan properties
UK companies and individuals bought most of these assets by volume (617) and value (£1.2 billion). Offshore entities held the rest, of which those incorporated in Jersey, the British Virgin Islands (BVI), Guernsey, and the Isle of Man owned 72 properties worth £813 million. Roughly speaking, UK companies acquired lower-value apartments whereas offshore companies purchased those at the higher end of the market.
Given this is a convenience sample and only focuses on cases where corruption is a potential predicate offence, the likely scale of illicit wealth invested through off-plan – including the proceeds of organised crime – is almost certainly more substantial.
Our analysis of this data identifies three weak points in the UK’s money laundering defences that need addressing:
- regulatory loopholes, with many developers having no obligation to ask awkward questions of buyers
- conflicts of interest held by conveyancers, which encourage them to turn a blind eye to money laundering risks
- high-risk commercial strategies targeting lucrative overseas buyers over the domestic market
This paper provides an overview of the evidence we have collected, including case studies, and proposes three recommendations that would help address these issues through more targeted policing of anti-money laundering rules. These proposals are of growing significance as the UK Government moves to increase the building of new properties, and are crucial to ensuring these homes help solve the housing crisis rather than making it worse.
Recommendations
To address the concerns raised in this analysis we propose three recommendations to address illicit funds being invested in the new-build property market.
Recommendation 1
Regulate developers for money laundering purposes
Government should use its forthcoming consultation on broadening the scope of the money laundering regulations to take a risk-based approach to supervising property developers.
Recommendation 2
Transparency over developer panels
Solicitors should report annually their membership of developer panels to their anti-money laundering supervisor.
Recommendation 3
Increase scrutiny of firms working for higher-risk overseas buyers
To help anti-money laundering supervisors take a risk-based approach to overseeing firms, solicitors should have to report annually whether they have been conveyancing properties for higher-risk clients from overseas.
Note we use solicitors as short-hand for those engaged in conveyancing activities covered by Regulation 12(1)(a) of The Money Laundering, Terrorist Financing and Transfer of Funds (Information on the Payer) Regulations 2017.
Why is new-build attractive to money launderers?
Criminals might favour new-build property over the resale market for several reasons, including:
- they can be bought in bulk, allowing buyers to spread illicit investments over a range of assets, which may arouse less suspicion than a single, large purchase
- they enable the buyer to ‘flip’ the property, selling it on before completion, laundering their money, avoiding stamp duty, and keeping their name off the land register in the process
- there are disincentives for panel solicitors working with developers to understand the buyer’s source of funds
- developers often depend on pre-sales to finance the completion of the project, and are under no legal obligation to do due diligence on buyers, so have a strong incentive to look the other way
- off-plan properties may be sold at a discount, providing an opportunity to make a healthy profit when selling the asset on completion
In this insights paper, we explore three key vulnerabilities that undermine the UK’s ability to identify and respond to the money laundering risks posed by new-build developments.
Regulatory loopholes
Parts of the private sector are subject to anti-money laundering (AML) rules, providing the first line of defence against ill-gotten gains being invested into the property market. Estate agents, banks, and law firms are all required to conduct due diligence on buyers and sellers of property, identifying their sources of wealth and the overall money laundering risk they pose. Any suspicions of money laundering should be reported to the UK’s Financial Intelligence Unit, housed in the National Crime Agency (NCA).
Due diligence is more complex in new-build developments, with more firms involved in the sales process as well as different client relationships. The UK’s most recent national risk assessment for money laundering and terrorist financing, produced by HM Treasury and Home Office, highlighted that the diverse mix of professionals, often operating across borders, can make it unclear exactly who has carried out checks on a buyer.
Developers themselves are not required to be regulated for money laundering purposes if they are not selling properties in an estate agency capacity. The UK’s national risk assessment estimates 74 per cent of developers are not registered with an AML supervisor.
Buyers may also approach a developer through a buying agent, which can obscure the identity of the end-client (see Case study: Former Bangladeshi land minister). The case study below shows that while some developers may claim to undertake checks similar to those required under the money laundering regulations, these can be ineffective. Were there a legal obligation on the developer to enquire about the buyer’s identity and source of funds, these purchases might not have proceeded.
Case Study: Former Bangladeshi land minister
In 2024, Bloomberg reported that the then Bangladeshi land minister, Saifuzzaman Chowdhury, had acquired a vast UK property portfolio worth £170 million despite having a stated annual salary of around £10,000.
In the same year, a separate undercover investigation by Al Jazeera highlighted how Mr Chowdhury’s estate agent fixer, Ripon “Shawkhat” Mahmood, assisted the minister with property purchases, acting as an introducer to the developer, Berkeley Group.
Mr Mahmood’s estate agency firm – supervised for money laundering purposes by HMRC – claims to have £779 million worth of properties under management, £900 million worth of properties sold, and to have found buyers for apartments in over 145 developments.
Following the Al Jazeera investigation, Saifuzzaman Chowdhury claimed to be the subject of a politically motivated “witch-hunt” against people associated with the previous government. Ripon Mahmood told Al Jazeera he had carried out robust AML checks on Mr Chowdhury. A Berkeley Group spokesperson said, “We undertake due diligence on all buyers and comply with UK AML rules and obligations on a voluntary basis.”
In June 2025, the UK’s NCA secured freezing orders against Mr Chowdhury’s assets as part of a civil investigation.
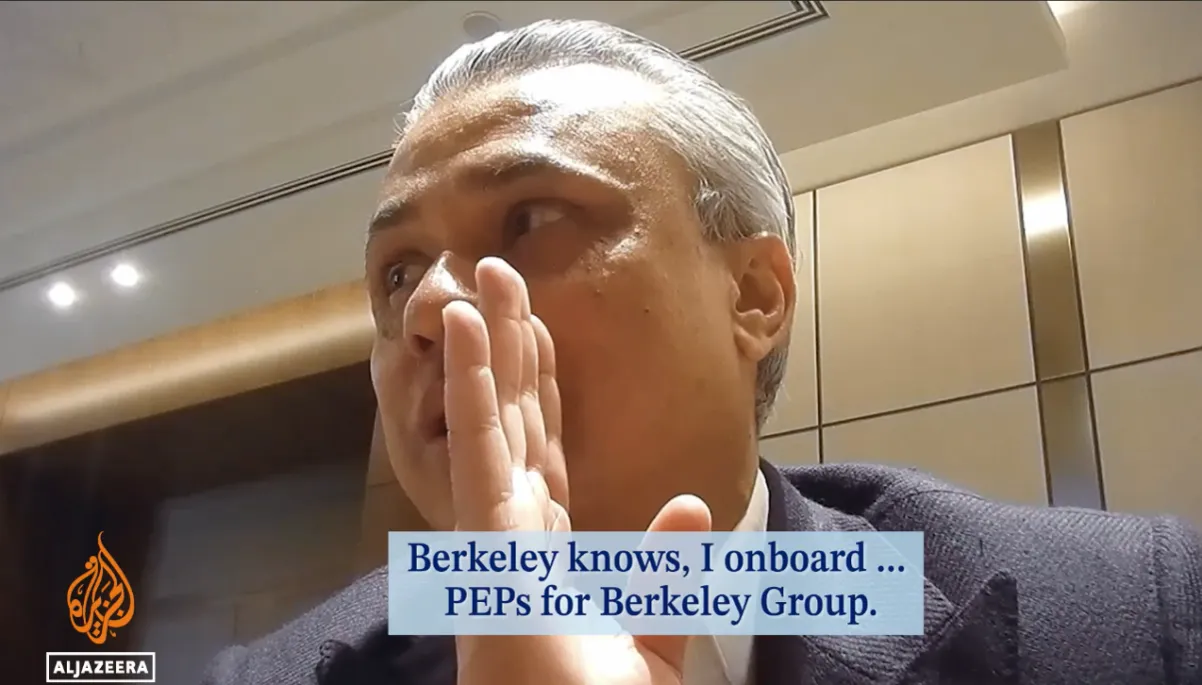
As well as client risks, there are also money laundering threats posed by some developers themselves. In total, we have identified 78 property titles worth £647 million being developed by landowners with suspicious wealth or developers with corruption and money laundering allegations against them (see Case study: Iranian-backed development for an example).
Our analysis indicates the risk primarily lies with those who have used suspicious wealth to acquire land and then seek to develop and sell property, enabling them to launder money on a larger scale in the process. Developers who work with these landowners are not required to conduct due diligence on them or their sources of funds. This is a critical shortcoming, adding weight to the argument that Government should include developers within the scope of the money laundering regulations.
Case Study: Iranian-backed development
In October 2025 the UK added “corrupt Iranian banker and businessman” Ali Ansari to its sanctions list, claiming he financially supported the Iranian Islamic Revolutionary Guard Corps.
Despite Mr Ansari being a politically connected individual from a country with a high risk of corruption, an Isle of Man company he controlled was able to gain planning permission to build 33 luxury apartments in North London in late 2024.
Recommendation 1
Regulate developers for money laundering purposes
Government should use its forthcoming consultation on broadening the scope of the money laundering regulations to take a risk-based approach to supervising property developers.
Conflicts of interest
Developers can have ‘panels’ of conveyancing firms they work with on projects, and towards whom they direct buyers. This can have some benefits – such as the firms’ familiarity with the site and lower costs for customers – but this practice has also attracted criticism. The Competition and Markets Authority has expressed concerns that the commercial incentives in these arrangements, where conveyancers are keen to avoid losing the recommendation of developers, could encourage firms to not represent the best interests of buyers.
While panel solicitors should be carrying out ‘know your customer’ checks on buyers, the commercial incentives involved can mean these are often not as rigorous as they should be. In some instances, hundreds of purchases are signed off by just one or two law firms that have a strong incentive to rubber-stamp questionable transactions because:
- the developer will often offer to pay the legal fees for buyers, which is a key source of income for the panel conveyancing firm
- firms do not want to be seen as obstructive and risk not being chosen on development panels for other projects
These are strong structural imperatives to push sales through, even when tough questions should be asked about a buyer’s source of wealth (see Case study: The former Heygate Estate and Elephant Park for an example).
Panel arrangements are not always easily identifiable, despite them providing important context to a firm’s risk profile. Those tasked with policing AML rules do not collect data on panel membership systematically, even though this could have a detrimental impact on firms’ customer due diligence work. Requiring solicitors to report panel membership annually, alongside the types of clients being engaged (see Recommendation 3 below), would enable AML supervisors to target their resources more effectively at higher-risk activity.
Recommendation 2
Transparency over developer panels
Solicitors should report annually their membership of developer panels to their anti-money laundering supervisor.
Case study: The former Heygate Estate and Elephant Park
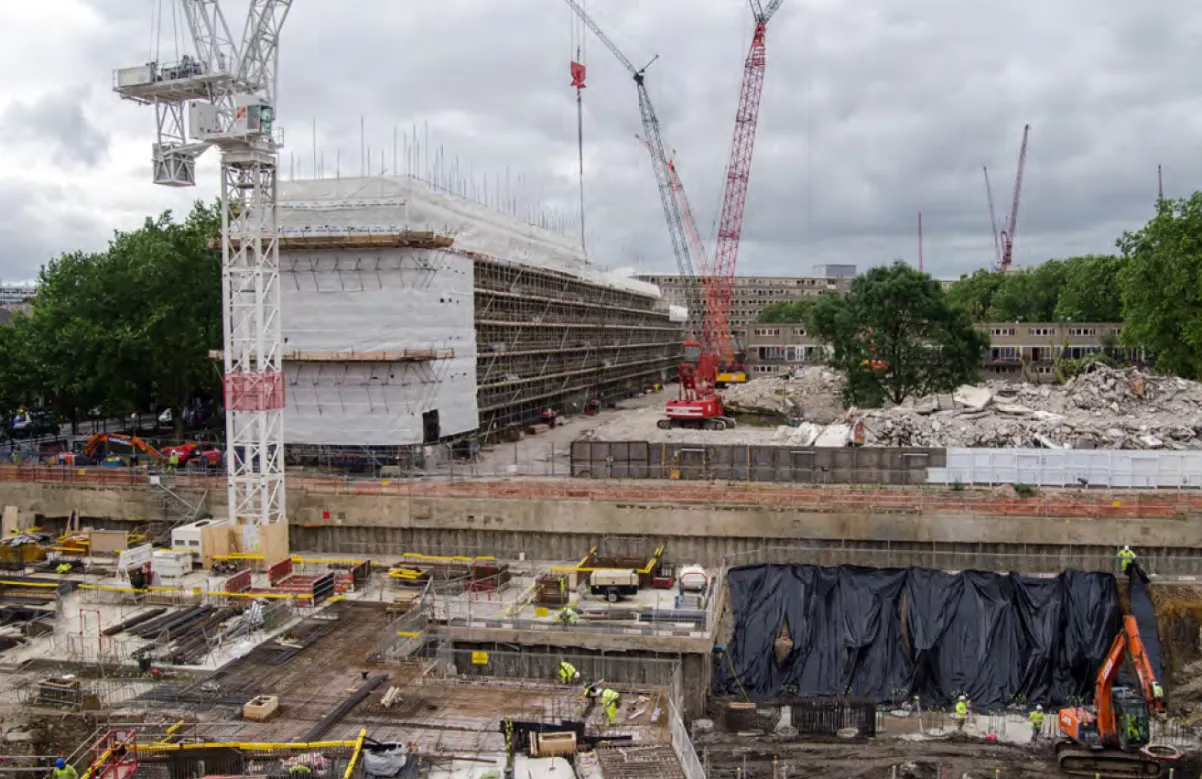
In 2016, we analysed off-plan purchases for the Elephant Park development on what was once the Heygate Estate in South London. The controversial site, which saw original residents forced to leave the area as the amount of affordable housing was slashed,
Riseam Sharples describes itself as a specialist in “advising Asian and other offshore investors in purchasing London property”.
A decade later, an investigation by The Times and the Organized Crime and Corruption Reporting Project (OCCRP) identified 19 apartments within the Elephant Park development bought by companies owned by Su Jiangbo – wanted by Chinese authorities for running an illegal gambling operation.
Riseam Sharples did not respond to the OCCRP’s multiple requests for comment by email and phone.
Su Jiangbo denies the charges against him, claiming the authorities in China are using them as a means to extort money.
High-risk commercial strategies
While there is a domestic market for mid-to-high-end new-build property, prices within these developments are often unaffordable for the average UK person, with small one-bedroom apartments in London often starting around £400,000. This has led developers to look overseas, where there are a seemingly endless number of people looking for an investment opportunity. Some build their own foreign-language websites to cater for this market, and work with sales agents abroad who hold promotional events for new developments.
Overseas marketing and a reliance on international investment to make developments profitable carry several money laundering risks. As a minimum, catering to investors from countries with higher levels of corruption and organised crime poses a higher aggregate risk than servicing domestic clients. Mitigating this risk through more robust customer due diligence might also prove difficult where there is limited or no free press in the buyer’s country of origin, and therefore few public domain sources of information about these high-end clients. And in a context where a panel solicitor is undertaking the checks, there is little commercial incentive for them to spend additional time and resources overcoming these challenges.
While these additional money laundering risks are not insurmountable, they are qualitatively different from those posed by domestic purchases. Our research found some instances where dozens of apartments in the same development were sold to those later sanctioned by the UK Government or subject to criminal investigation. In situations like this, when all suspect transactions were processed by just one firm, it raises serious questions as to whether the solicitors have sufficient AML systems in place to detect suspicious activity (see Case study: The Prince Group below).
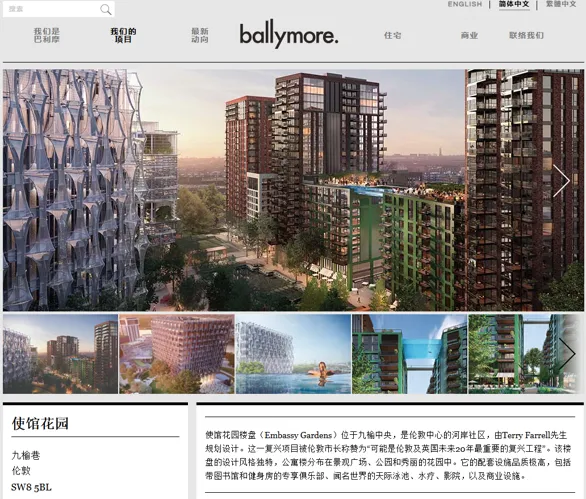
Ballymore’s Chinese language
website for its Embassy Gardens
development (see Case study:
The Prince Group below)
Where AML supervisors are overseeing thousands of firms, it is crucial they can identify higher-risk practice to deploy their resources effectively. However, they do not have granular enough data to do so. While solicitors must conduct business-wide risk assessments for money laundering, including whether they are conveyancing for overseas clients from a tightly defined list of “high risk jurisdictions”,
Recommendation 3
Increase scrutiny of firms working for higher-risk overseas buyers
To help anti-money laundering supervisors take a risk-based approach to overseeing firms, solicitors should have to report annually whether they have been conveyancing properties for higher-risk clients from overseas.
Case Study: The Prince Group
On 14 October 2025, the UK’s Foreign, Commonwealth and Development Office sanctioned the Prince Group
Members of the Prince Group, who originated in China and moved to Cambodia, invested over £280 million into UK property, with much of this going into new-build apartments. Wei Ren Qiu – the cousin of the group’s leader, Chen Zhi – used UK companies to acquire 17 properties for almost £27 million across two developments: Battersea’s Embassy Gardens and Centre Point Tower in Central London.
Yihua Yuan is not currently sanctioned in the UK, and he did not respond to previous requests for comment about the CPS applying to freeze his real estate.
The conveyancer for all of these new-build purchases was law firm Chan Neill Solicitors LLP. The firm cites its Chinese-language services as one of its unique selling points, with a Mandarin version of its website also available.
At the time of purchase in 2021 there was already media coverage in the public domain highlighting numerous risks around the Prince Group and its operations.
Conclusion
Thanks to transparency reforms over the past decade, we are able to identify suspect investments into the UK property market, at scale. Analysing this data we have spotted a crucial weakness in our country’s defences against illicit funds: off-plan purchases, where there is a strong incentive for lawyers processing transactions to look the other way. At the same time, the developers profiting from these sales have no obligation to question where the money is coming from, even if it looks like it could be the proceeds of crime. This wilful blindness has allowed billions of pounds in questionable funds to enter our economy, a substantial amount of which is now frozen by UK authorities.
While recent large-scale asset seizures are welcome, the challenge at hand is not one we can address through enforcement alone. Stopping the money upstream is crucial if we want to end the UK’s reputation as a haven for ill-gotten gains, and prevent illicit wealth from distorting our housing market. With better data and more eyes on the issue, we can make more targeted interventions to make sure businesses are not rolling out the red carpet for kleptocrats and organised crime.